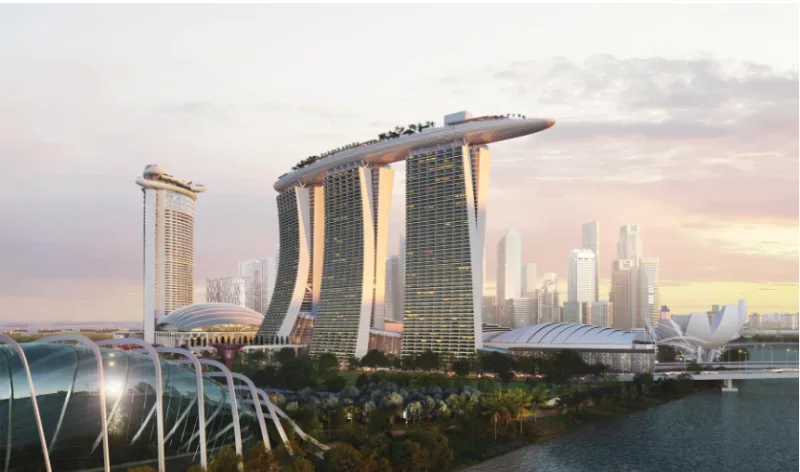
Moody's has affirmed Las Vegas Sands' Baa3 investment-grade rating and a Baa2 rating for Macau subsidiary Sands China. The outlook for both remains stable despite heavy capital spending on the Marina Bay Sands expansion in Singapore and other projects.
Analysts expect LVS to hold debt at around three times EBITDA during the development phase. Moody's said the MBS expansion will attract significant additional traffic and deliver 'substantial earnings', strengthening the group's ability to deleverage. In the first half of 2026 Marina Bay Sands posted an adjusted EBITDA margin of approximately 50%.
As of 30 June LVS held $3.38bn in cash and equivalents, plus $4.26bn in available credit lines. Marina Bay Sands separately has access to $4.68bn under a deferred $5.88bn facility. Moody's expects the company to meet covenants and debt maturities on schedule.
The main risk is the scale of development commitments. If new integrated resort projects are funded mainly through debt, leverage may rise for extended periods. Continued dividend payments, share buybacks and secured debt for construction could also constrain the credit profile.
A downgrade may occur if liquidity deteriorates, Macau operations stall, or debt stays above three times EBITDA for long. An upgrade would require debt below two times EBITDA alongside stable revenue and margin growth.


