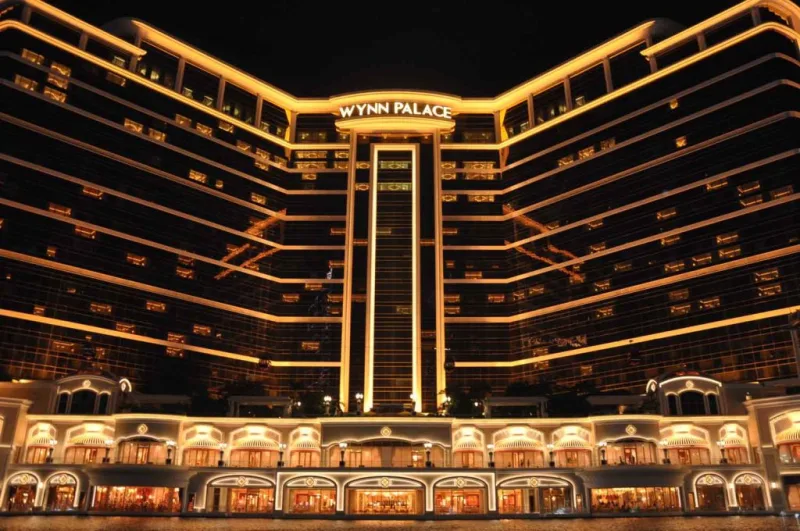
Wynn Resorts Finance and Wynn Resorts Capital priced $900 million in notes at 6.875%, maturing in 2035. The deal is expected to close on 22 September.
Proceeds, together with existing cash, will go to subsidiary Wynn Las Vegas to redeem its 5.25% notes due in 2027 and cover transaction costs. Fitch assigned the new notes a BB- rating and called the refinancing 'leverage-neutral' — it replaces existing debt rather than funding new projects directly.
The agency still expects the group's debt-to-EBITDA ratio to climb to 6.0x in 2026 from 5.8x in 2025, driven by capital needs for Wynn Al Marjan Island in the UAE and the Wynn Palace expansion in Macau. Fitch sees leverage remaining near the upper end of the downgrade threshold for the next few years until those projects complete.
Wynn holds a 40% stake in the $5.7 billion Al Marjan project, scheduled to open in September 2027. Fitch believes the property will strengthen the credit profile once operational, but flags risks around timing, cost and demand.
The ratings are supported by strong positions in Macau and Las Vegas, a quality asset base and adequate liquidity. Limited diversification and heavy capital spending may slow credit improvement. For Macau, Fitch expects mid-single-digit EBITDA growth in 2026, then moderate gains through 2029 amid uncertainty in China's economy and promotional pressure in the market.


