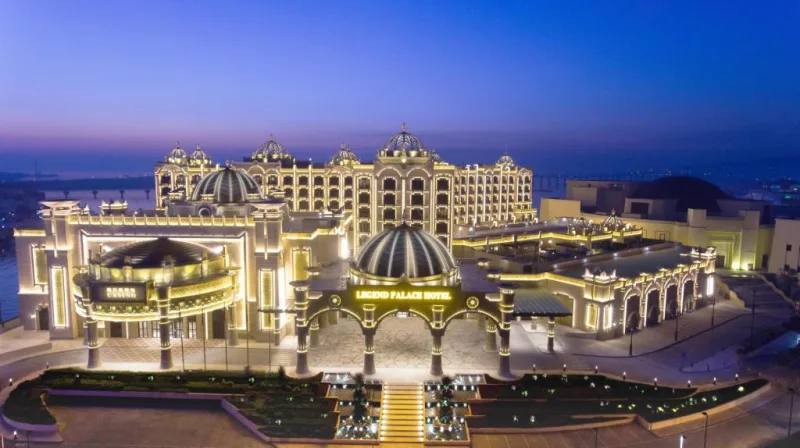
Macau Legend Development posted an adjusted EBITDA profit of HK$8.8m ($1.1m) in the first half of 2026, reversing a HK$0.1m ($13,000) loss a year earlier. Revenue from continuing operations, now entirely non-gaming, rose 2.7% to HK$172.65m ($22.1m). The improvement came from lower staff costs, down HK$5.6m ($718,000), and reduced inventory expense, down HK$4.3m ($551,000).
The Legend Palace casino, which operated under a service agreement with SJM Resorts, contributed HK$175.1m ($22.4m) in the first half of 2025 before the parties terminated the contract on 13 November that year. Net loss narrowed to HK$136.8m ($17.5m) from HK$1.42bn ($182.2m), when the group wrote down HK$1.27bn ($163.1m) in Macau asset impairments ahead of the casino closure.
Hotel occupancy remained strong: Legend Palace Hotel reached 91.2% at an average rate of HK$929 ($119) per room, while Harbourview Hotel hit 91.0% but saw its rate fall to HK$671 ($86) from HK$766 ($98). Room revenue climbed HK$6.2m ($795,000) after all Legend Palace rooms became available for third-party sale instead of gaming use.
The financial position remains critical. Current liabilities exceeded assets by HK$2.68bn ($343.7m) at 30 June, with cash balances of HK$37.9m ($4.9m). Debt of HK$2.39bn ($306.6m) falls due within twelve months. The company is in breach of minimum net asset and leverage covenants; creditors can demand immediate repayment of HK$2.05bn ($263.1m). An in-principle agreement on restructuring was reached with banks in August 2026, but no formal deal has been signed. Auditor Baker Tilly Hong Kong withheld its conclusion on the company's ability to continue as a going concern.


